

Cap Cost Reduction vs Down Payment vs Start Fee
June 24, 2022
Cap Cost Reduction vs Down Payment vs Start Fee
A cap cost reduction is the money you put down on a lease, the lease world's version of a down payment. It lowers your monthly payment by reducing the amount being financed, but unlike a down payment on a loan it buys you no equity, and you do not get it back.
That distinction is the whole decision, and it is the one most explainers skip. Below, each of the three kinds of money down gets defined on its own terms, then compared in a single table: a down payment on a loan, a cap cost reduction on a lease, and a start fee on a car subscription. Autonomy runs the subscription fleet, so the start-fee numbers are our posted catalog pricing as of September 2026, and the loan and lease figures name their outside sources. We will also show you the one case where paying more up front provably saves you money, and the point where it stops.
What is a cap cost reduction?
A cap cost reduction, short for capitalized cost reduction, is any cash, trade-in, or rebate applied at lease signing to lower the capitalized cost. The Federal Reserve's leasing guide describes it as being like a down payment when buying a car, and it lowers your monthly payment.
Mechanically, the lease starts from a gross capitalized cost, roughly the agreed vehicle value plus any fees rolled in. Your cap cost reduction is subtracted from it, leaving the adjusted capitalized cost that your payment is actually calculated on. Lower adjusted cap cost, lower payment.
It does two things to your monthly bill, and the Federal Reserve names both: it shrinks the depreciation you pay across the term, and it lowers the rent charge, because the rent charge is calculated on a smaller starting balance. So a cap cost reduction is not purely a prepayment. It does reduce what you pay in financing costs.
What it does not do is create anything you own. You are lowering the payment on a car you will hand back, and that money is generally not returned to you and does not become equity. That is the part worth sitting with before you write the check.
There is usually a ceiling, too. The Federal Reserve notes that most lessors cap how much you can put down, commonly at 20% of MSRP or 20% of the vehicle's value. On the $50,089 average new-vehicle transaction price Kelley Blue Book recorded in August 2026, that works out to a limit around $10,000.
What is a down payment, and how is it different?
A down payment is cash you put toward buying a car, so it reduces the loan principal and the interest that accrues on it. It is the only one of these three payments that buys equity, a stake in the car you can later sell.
This is the version most drivers know, and it is genuinely the strongest of the three on pure cost. Every dollar down is a dollar you never borrow, so you never pay interest on it. Bankrate, citing Edmunds data for the second quarter of 2026, puts the average new-car down payment at $5,815 and the average used-car down payment at $4,016, figures we retrieved in September 2026.
The honest version: a down payment is not risk-free either. Money sunk into a depreciating asset is money you cannot easily get back out, and if the car is totaled early, your insurance settlement follows the car's value, not what you paid toward it. But the car itself remains yours to sell, which is a real asset the other two options never give you.
What is a start fee?
A start fee is the upfront amount you choose when you subscribe to a car at Autonomy, and a higher start fee buys a lower monthly payment. A subscription is not a lease: there is no financed balance, no residual value, and no lease term.
Every priced car in our lineup posts the same three plans as of September 2026, and the start fee is the only thing that separates them: Explore at $1,000, Experience at $2,000, and Enjoy at $3,000. Monthly payments across the fleet run $300 to $700 depending on the car and the plan you pick.
Our own vehicle pages describe the start fee as being like a down payment, commonly called a cap cost reduction in traditional leases, and that comparison is fair as far as the payment math goes. It is not fair as a description of the contract. There is no multi-year term to break, no residual value set in advance, no buyout deadline, and no disposition fee at the end.
What replaces the term is a short commitment and a notice period: a 31-day minimum hold, then 14-day notice whenever you want to hand back the keys. The monthly payment covers 1,000 miles a month, with additional miles at $0.25 each, plus registration, routine maintenance, and roadside assistance. For the full mechanics, see how a car subscription works.
Here is the concession, and it matters: when you cancel, your start fee does not come back. Our subscription terms make the drive-off payment non-refundable during the initial term, with the refundable security deposit as the exception. There is one narrow refund path, and it is not yours to trigger: if Autonomy or our financing partners end the agreement inside your first 12 months and the car comes back in good condition, the start fee is refunded pro rata. On that specific point, a start fee behaves much like a cap cost reduction. Money committed up front is money committed.
Down payment vs cap cost reduction vs start fee
The three payments look identical at the signing table and behave differently everywhere else. This is the comparison in one place:
| Down payment (loan) | Cap cost reduction (lease) | Start fee (Autonomy subscription) | |
|---|---|---|---|
| What it reduces | The loan principal | The adjusted capitalized cost | The monthly payment only |
| Cuts financing costs | Yes, less principal accrues interest | Yes, a smaller balance means a smaller rent charge | No interest or rent charge exists; it shifts when you pay |
| Builds equity you can sell | Yes | No | No |
| Returned if you end early | No, but the car is yours to sell | Generally no | No when you cancel; pro rata only if we end the agreement inside 12 months |
| Typical or posted amount | $5,815 average, new, Q2 2026 | Commonly capped at 20% of MSRP | $1,000, $2,000, or $3,000 posted |
| Who sets the ceiling | You and the lender | The lessor | Posted publicly, same three tiers on every car |
| Commitment it buys into | Loan term, typically 5 to 7 years | Fixed lease term, typically 24 to 36 months | 31-day minimum, then 14-day notice |
Sources for the amounts above, in order: Edmunds via Bankrate for the Q2 2026 down-payment average, the Federal Reserve for the lease cap, and our own posted plans as of September 2026 for the start fee.
Which one actually saves you money?
On a loan, more money down genuinely lowers your total cost, because less principal accrues interest; on a lease it mostly moves money forward. On an Autonomy subscription the answer is a date: every extra $1,000 of start fee buys $50 a month, so month 20 is break-even.
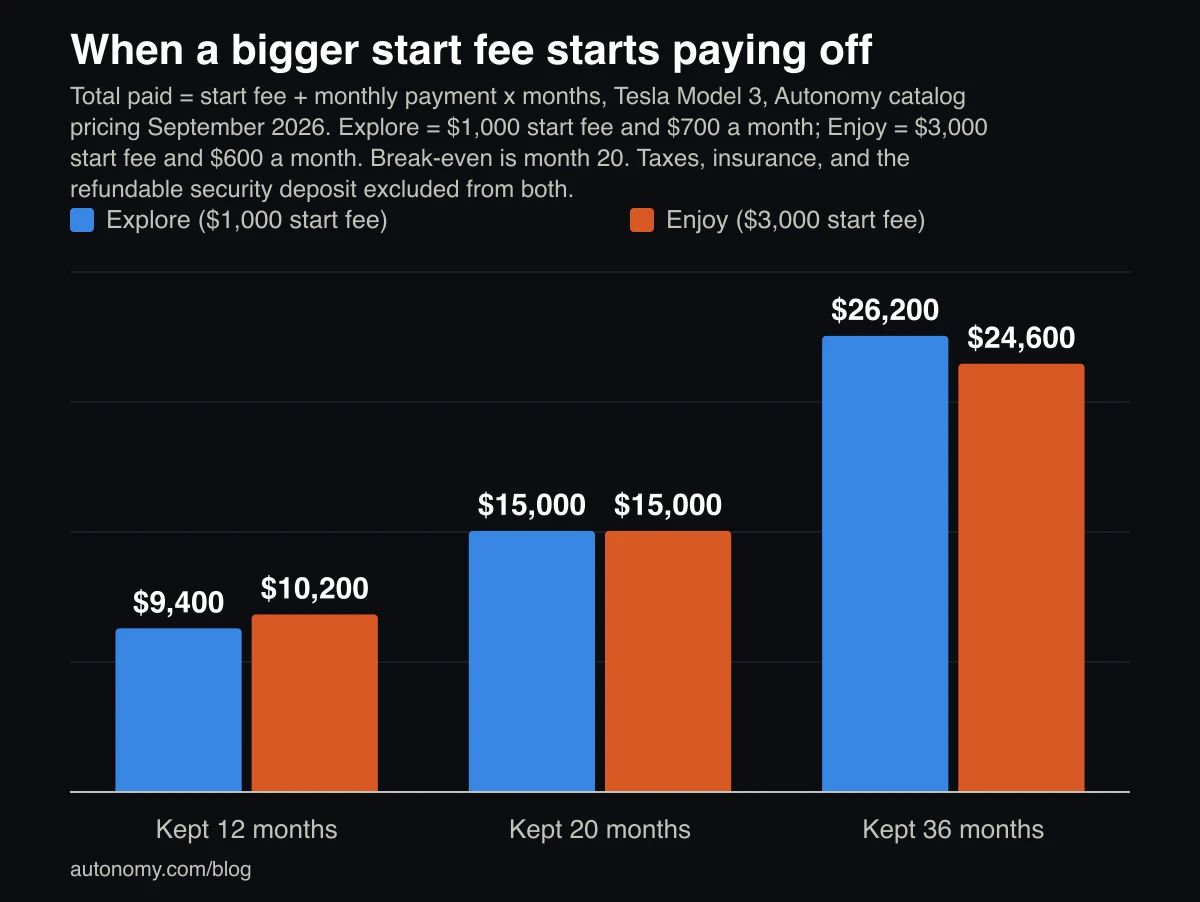
That $50 figure is not an average or an estimate. We checked it across all 13 priced models in the lineup as of September 2026, and the step is identical on every one of them: each $1,000 of additional start fee takes exactly $50 off the monthly payment. Divide $1,000 by $50 and you get 20 months, which means the break-even point is the same whether you are pricing a Ford Bronco Sport or a BMW i4.
So the decision has a clean rule. Keep the car longer than 20 months and the bigger start fee wins; give it back sooner and the smaller one does. As the chart shows, at 12 months the $1,000 Explore plan on a Model 3 leaves you $800 better off, and at 36 months the $3,000 Enjoy plan is $1,600 ahead, all on September 2026 pricing.
A lease has no equivalent rule, because the term is fixed for you. A loan has one, but it runs the other way: the longer you hold, the more a down payment saves you in interest, with no crossover point to find.
How much should you put down?
Put down what the math supports, not what lowers the payment most: on a loan, a larger down payment reliably cuts total interest. On a lease or a subscription, only commit cash you will not need back, because neither one returns it when you leave.
Three practical reads, depending on which one you are signing:
- Buying with a loan. More down is straightforwardly cheaper. Weigh it only against what else the cash could do and against your own need for a reserve.
- Leasing. Many advisers suggest keeping the cap cost reduction small, because you are prepaying a payment stream on a car you will return. Lowering the monthly is the benefit; there is no ownership stake at the end of it.
- Subscribing. Answer one question first: will you keep this car longer than 20 months? If yes, the larger start fee is the cheaper path. If you are not sure, take the smaller one, since flexibility is the thing you are paying for.
If you want to run this against a real car rather than a formula, a Tesla Model 3 subscription starts at $600 a month on the Enjoy plan plus its one-time start fee, and the side-by-side subscription and lease comparison shows the same cost logic applied across a full term.
Frequently asked questions
Is a cap cost reduction the same as a down payment?
They work the same way at signing and differ afterward: a down payment on a loan builds equity in a car you own, while a cap cost reduction lowers payments on a car you will return.
Does a cap cost reduction lower your total lease cost?
Yes, modestly, because a smaller starting balance means a smaller rent charge, but most of what you pay up front is simply payment you would have made later.
What does cap cost mean on a lease?
Capitalized cost is the amount the lease payment is calculated from, starting with the agreed vehicle value plus any fees rolled in, before your cap cost reduction is subtracted.
Do you get a cap cost reduction back if you end the lease early?
Generally no, which is the main argument for keeping it small; the money has already been applied to the lease and does not convert into equity you can recover.
Is an Autonomy subscription a lease?
No. A subscription is not a lease or a type of lease: you pay month to month with no financed balance, no residual value, and no fixed term to break.
What is a start fee on a car subscription?
It is the one-time amount you choose up front, and it sets your monthly payment: on September 2026 pricing, each $1,000 of start fee lowers the monthly by $50 on every car we post.
The upfront number is the easiest one to be talked into and the hardest to undo, so it is worth pricing deliberately. Compare the full cost of a subscription against a lease on our car subscription versus lease breakdown, or see the posted plans for every car on the Autonomy vehicles page.